
Editor's note: Some exceptional companies are buried...
While some large companies perform well, they might have an underlying segment that could truly thrive if it were split off from the main business. When that happens, history shows that these businesses can perform well... even beating out their parent companies.
In today's Masters Series, adapted from a Market Maven special report, editor Gabe Marshank explains how you can outperform an already good business by finding its hidden gem...
Uncle Carl's Method That Can Beat the Market
The first things I noticed about Uncle Carl's office were the "tombstones"...
This wasn't any average office, and he wasn't any average uncle.
On Wall Street, investment banks like to commemorate big transactions. Initial public offerings ("IPOs"), mergers, acquisitions – all of them get a collectible glass sculpture.
On the 47th floor overlooking Central Park, Carl Icahn had an office stuffed with them – each for a corporate scalp.
He's one of the most famous (or perhaps infamous) activist investors. He made a name for himself in the 1980s as a "corporate raider" for his proxy battles with Trans World Airlines, eventually acquiring the company in 1988. He'd pick more fights with RJR Nabisco, Western Union, Yahoo!, and several others over the years.
"Uncle Carl" is his surprising nickname. He has a boyish charm and a friendly personality – until he gets down to business. Then he's all teeth.
At the time, I was working for Steve Cohen's SAC Capital Advisors. One of my colleagues at the firm had come up with a long-shot plan to pressure a company to spin off a segment of its business.
We ultimately abandoned the idea. But the reason we got the meeting in the first place was because we agreed with Uncle Carl on a fundamental truth: Spinoffs create value.
For the uninitiated, a spinoff is when a larger parent company gives its owners newly created shares in a subsidiary that will trade separately from its former parent.
Icahn had used this strategy in the legendary battle chronicled in Barbarians at the Gate.
In the late '90s, RJR Nabisco had heavy debt and an awkward group of food and tobacco assets. Icahn bullied the company into a separation that allowed both stocks to realize their full value... and made $1 billion along the way.
He struck again in 2014.
In 2002, eBay (EBAY) acquired PayPal (PYPL) for $1.5 billion. And from then on, the PayPal business existed within the eBay parent company. Icahn wanted that to change.
In an open letter to eBay's board, dated February 24, 2014, Icahn articulated the case for this spinoff. What strikes me, a decade later, is that this is the perfectly stated case for spinoffs in general:
We believe creating two dedicated and highly focused independent businesses would provide employees and stockholders the best opportunity to remain competitive over the long term.
We believe that the separation of the traditional eBay and PayPal businesses will: (1) highlight the significant value of the disparate businesses currently shrouded by a conglomerate discount the market has afforded eBay; (2) focus and empower independent management teams to most effectively build two very different business platforms, make economic decisions independent of each other and, most importantly, foster innovation; and (3) provide an even more valuable currency for future bolt-on acquisition opportunities and for recruiting the top talent necessary for PayPal to remain the market leader in payment technology.
Icahn would eventually get his way.
In 2015, eBay decided to spin off PayPal, creating two separate companies.
If you owned EBAY shares at the time, you automatically received new shares of PYPL. Specifically, for every EBAY share you owned, you received one share of PYPL on top of it.
There was no need to fill out any paperwork or take any special action – the new PYPL shares simply appeared in your brokerage account as part of the spinoff.
And whether the eBay board wanted to admit it at the time or not, Icahn's proposal was a smart one.
The transaction let eBay focus on being an online marketplace where people buy and sell goods, while PayPal could expand in the electronic-payments world and work with many different retailers.
For retail investors, the spinoff meant more potential opportunity. Now, each company could make decisions that were best for its future without having to compromise for the other.
Investors suddenly had a stake in both an e-commerce leader and a major player in online payments.
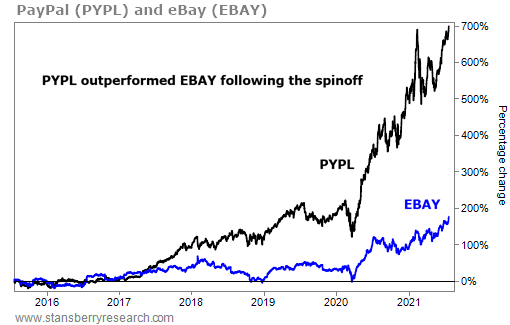
As you can see in the chart below, over the following six years, EBAY shares nearly tripled... But investors who held their PYPL shares fared far better – up more than 720%. Take a look...
The eBay/PayPal spinoff isn't a cherry-picked example...
In 2013, healthcare products maker Abbott Laboratories (ABT) spun off AbbVie (ABBV) to focus on pharmaceuticals. AbbVie's blockbuster arthritis drug Humira drove rapid growth, propelling ABBV shares to more than triple the performance of ABT shares since the spinoff...

In 2000, business-information company Dun & Bradstreet spun off credit-ratings agency Moody's (MCO). Moody's grew faster and delivered much higher returns than its parent company in the years following the split. Today, Moody's is up more than 3,200% since the spinoff and is valued at roughly $80 billion, while Dun & Bradstreet went private last year in a deal worth around $8 billion.

More recently, utility giant Exelon (EXC) spun off Constellation Energy (CEG), which focuses on renewable energy and power generation.
Since the split, Exelon shares are roughly flat... while Constellation shares are up more than 300%...

A 1993 study from Pennsylvania State University found that spinoffs outperformed the overall market by an average of 30% over three years.
When I started on Wall Street in 1997, this was the report that was fresh in everyone's mind: Suddenly, every hedge fund was looking at spinoffs.
The spinoff trade has continued to work. I could tell you about study after study that proves it, but it's easier to show you instead. The following chart compares the Bloomberg U.S. Spinoff Index – which tracks companies recently spun off – with the broad S&P 500 Index over the past five years.
As you can see, the S&P 500 has done great, up nearly 100%... But the spinoff index has absolutely trounced it, up about 500%...

That's why every hedge fund I ever worked at – Greenlight Capital under David Einhorn, SAC Capital under Steve Cohen, and Omega Advisors under Leon Cooperman – took a long, hard look at any spinoff.
There's a simple reason for why spinoffs are such fertile ground for investors: Because they make no money for Wall Street.
This may sound counterintuitive, but I'll explain everything in detail in tomorrow's issue.
Regards,
Gabe Marshank
Editor's note: Many investors are overlooking an untapped segment of the market. Meanwhile, major institutions either can't buy these quality companies or are being forced to sell them. But it won't be long before these businesses explode.
Gabe has spotted an opening to get in and buy fantastic companies below their true worth. It has nothing to do with the latest market trend. But if you want to use the same strategy that some of the greatest investors use, you need to hear Gabe's message.
